Ontario Loan Agreement Template | Free Download & Legal Guide
Ontario Loan Agreement is the safest way to protect your money when lending to someone—whether it’s a friend, family member, or business partner.
Imagine lending $5,000 CAD to a friend. Everything feels fine—until repayment gets delayed or denied. Without a formal written agreement executed in compliance with the Ontario Evidence Act, proving the exact parameters of the debt obligation can become an evidentiary nightmare in a court of law.
I’ve seen Ontario lenders lose thousands because they relied on text messages or verbal promises that were impossible to properly enforce later. In Ontario, private loan defaults up to a maximum threshold of $35,000 CAD fall under the jurisdiction of the Small Claims Court pursuant to O. Reg. 626/00 of the Courts of Justice Act. Without explicit written terms detailing the dynamic of repayment, simple interpersonal advances are frequently mischaracterized as gifts, frustrating recovery attempts.
Last Updated: September 2026
Free Ontario Loan Agreement Template
Below is a simple and practical template you can use right away. Just fill in the details.
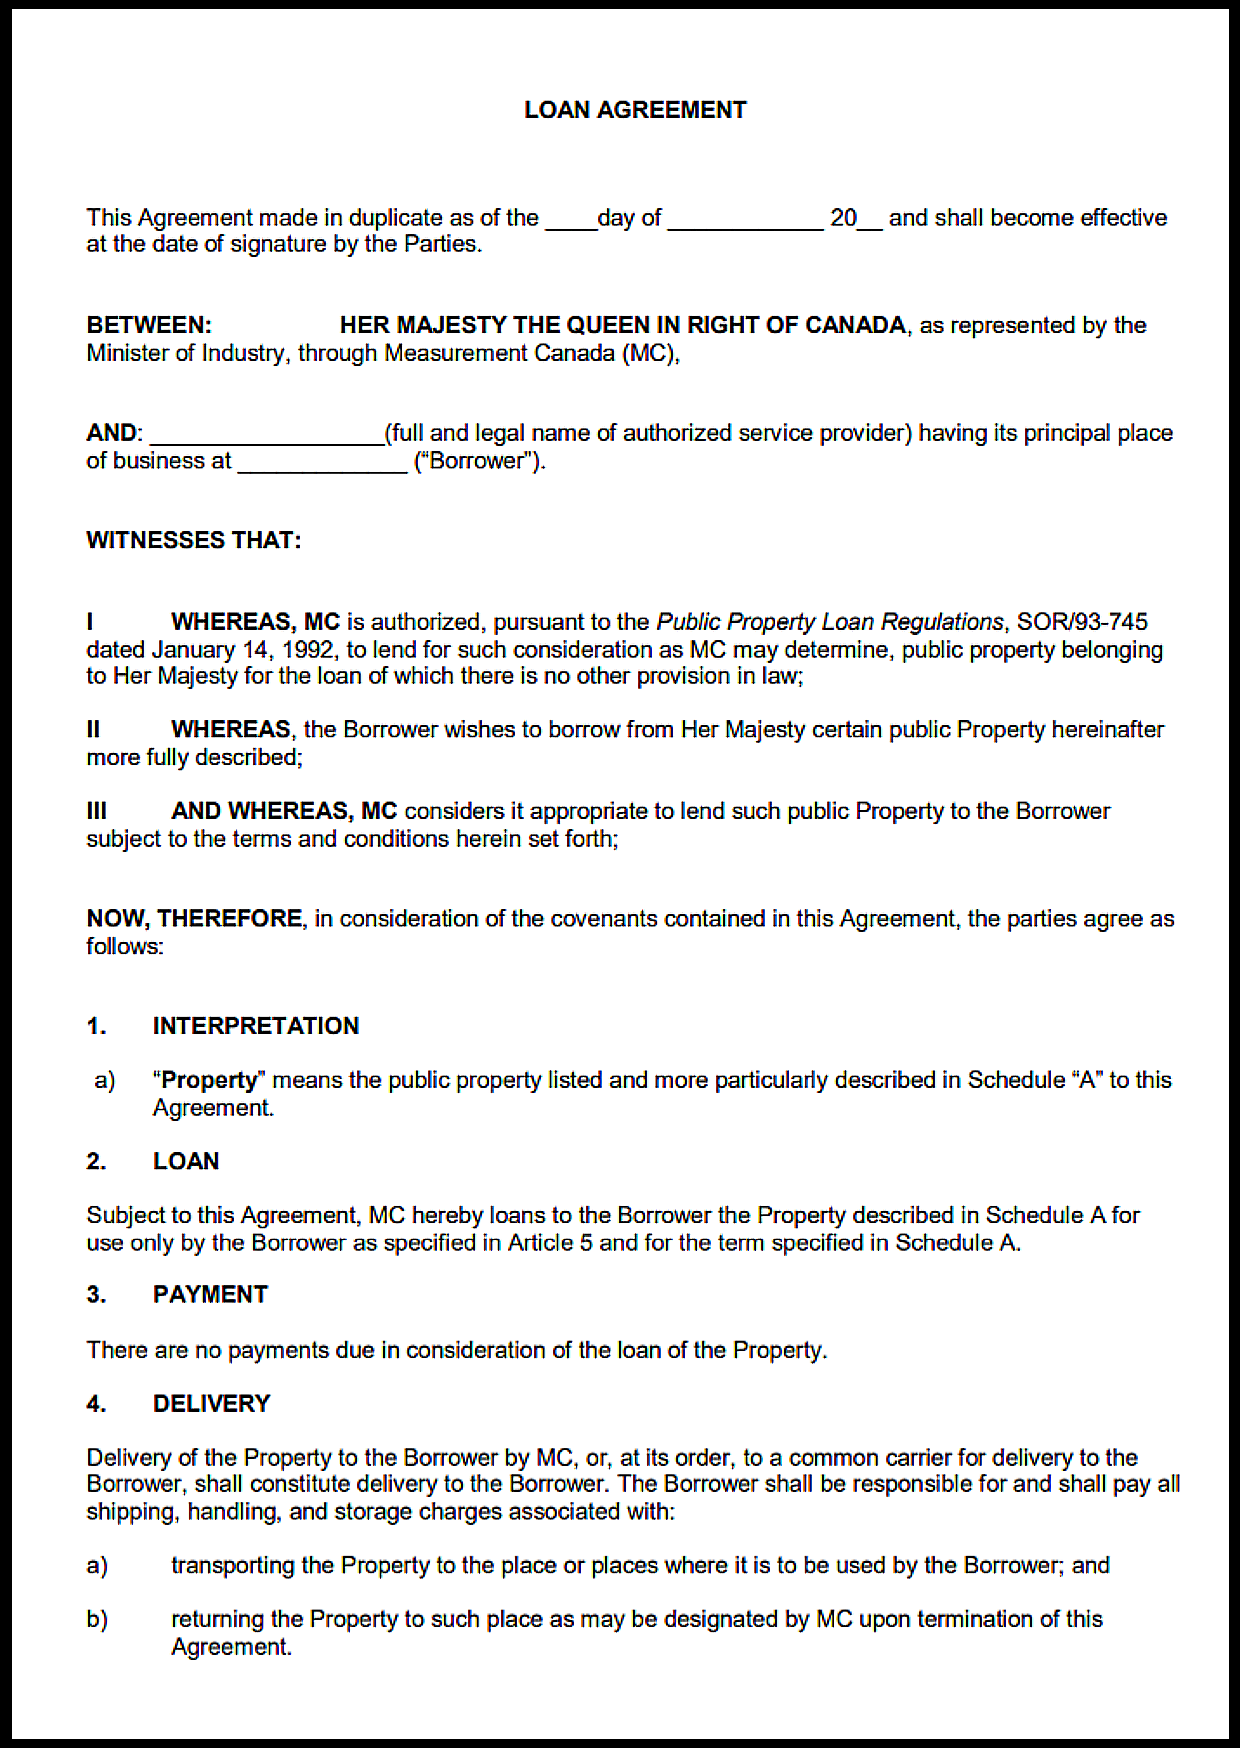
Tip: Always keep a signed copy for both parties. Digital and physical copies are both helpful.
Ontario Loan Agreement Laws and Borrowing Rules You Should Know
| Topic / Issue | Ontario Legal Rule | Governing Statute |
|---|---|---|
| Federal interest regulation | Federal law, including the Interest Act, can affect how interest is stated and calculated in Ontario loan agreements. | Interest Act, RSC 1985, c I-15 |
| Consumer loan protection | Certain consumer credit agreements may be subject to Ontario’s Consumer Protection Act, 2002 and its regulations, depending on the parties and type of credit agreement. | Consumer Protection Act, 2002, S.O. 2002, c. 30, Sched. A |
| Commercial loan governance | Commercial lending can involve Ontario contract and commercial law, federal interest rules, and additional legislation depending on the transaction and any security provided. | Ontario contract and commercial law; applicable federal legislation |
| Recent consumer law reform | Ontario’s current consumer-credit rules remain primarily governed by the Consumer Protection Act, 2002 and applicable regulations; the Consumer Protection Act, 2023 has been enacted but is not yet in force. | Consumer Protection Act, 2002; Consumer Protection Act, 2023 |
| Who can sign | A loan agreement should be signed by each party or by a person who has proper authority to bind the individual or organization on whose behalf they sign. | Contract law and applicable corporate/agency principles |
| Witness requirement | An ordinary loan agreement does not generally require a witness merely because it is a loan agreement. Different requirements may apply to deeds or documents involving specific forms of security. | Ontario contract and property law |
| Notarization requirement | An ordinary loan agreement generally does not need to be notarized, although a related transaction or document may have separate witnessing, commissioning or registration requirements. | Ontario law |
| Minimum age requirement | Ontario’s age of majority is 18. Contractual capacity for a person under 18 can depend on the nature and circumstances of the agreement. | Age of Majority and Accountability Act, R.S.O. 1990, c. A.7 |
| Mental capacity requirement | Contractual capacity can depend on whether a party was capable of understanding the nature and consequences of the agreement and on the circumstances known to the other party. | Ontario common-law principles |
| Deadline to sue for unpaid debt | A claim is generally subject to Ontario’s two-year basic limitation period, running from when the claim is discovered, subject to the Limitations Act, 2002 and its exceptions. | Limitations Act, 2002, S.O. 2002, c. 24, Sched. B |
| APR disclosure requirement | Where the Consumer Protection Act, 2002 applies to a consumer credit agreement, the agreement must meet the applicable disclosure requirements, which can include disclosure of the annual percentage rate. | O. Reg. 17/05 under the Consumer Protection Act, 2002 |
| Cost of borrowing disclosure | For consumer credit agreements covered by Part VII of the Consumer Protection Act, 2002, applicable disclosure rules can require information about the cost of borrowing, interest and other charges. | O. Reg. 17/05 under the Consumer Protection Act, 2002 |
| Borrower prepayment rights | Certain consumer credit agreements provide statutory rights concerning prepayment and refunds of applicable borrowing costs; the specific rules depend on the type of credit agreement. | Consumer Protection Act, 2002 and applicable regulations |
| Annual interest disclosure rule | If a written contract states interest for a period shorter than a year, section 4 of the Interest Act requires an express statement of the equivalent yearly rate to recover interest above 5% per annum. | Interest Act, RSC 1985, c I-15, s. 4 |
| Filing requirements for unsecured loans | An ordinary unsecured loan does not generally require registration merely because it is a loan. | Ontario contract law |
| Registration of secured loans | Where a lender takes a security interest in personal property, registration of a financing statement under Ontario’s Personal Property Security Act may be necessary to perfect the security interest, depending on the circumstances. | Personal Property Security Act, R.S.O. 1990, c. P.10 |
| Criminal interest rate limit | Under s. 347 of the Criminal Code, an annual percentage rate exceeding 35% is generally a criminal rate of interest, subject to statutory exceptions and regulations. | Criminal Code, RSC 1985, c C-46, s. 347 |
| Unconscionable lending practices | Ontario law contains protections against certain unfair or unconscionable consumer practices, but the applicable statutory provision depends on the transaction and whether the Consumer Protection Act, 2002 applies. | Consumer Protection Act, 2002 and applicable law |
| Failure to disclose annual interest | If section 4 of the Interest Act applies and a written contract does not state the required equivalent yearly rate, interest above 5% per annum may not be chargeable, payable or recoverable. | Interest Act, RSC 1985, c I-15, s. 4 |
| Ontario’s strict limitation period | Ontario generally applies a two-year basic limitation period, but the start date and possible extensions or exceptions depend on the Limitations Act, 2002 and the circumstances of the claim. | Limitations Act, 2002 |
| Ontario PPSR registration system | Ontario uses a Personal Property Security Registration system for registering financing statements relating to security interests in personal property. | Personal Property Security Act |
| Ontario consumer protection scope | Ontario’s current consumer-credit rules include disclosure and other protections for covered consumer transactions under the Consumer Protection Act, 2002 and its regulations. | Consumer Protection Act, 2002 |
One important rule in Ontario loan agreements is the federal Interest Act. Section 4 applies when a written contract states interest for a period shorter than one year, such as a monthly or daily rate. To recover interest above 5% per annum, the contract must contain an express statement of the equivalent yearly rate.
Another important issue is Ontario’s limitation period. A claim is generally subject to a two-year basic limitation period from when the claim is discovered, but the Limitations Act, 2002 contains discoverability rules and exceptions. The timing can also depend on the nature of the debt and when payment became due.
The federal criminal interest-rate framework also matters. Under s. 347 of the Criminal Code, an APR exceeding 35% is generally a criminal rate of interest. The Criminal Interest Rate Regulations create specific exceptions for certain business or commercial borrowings. For example, where the borrower is not a natural person and the borrowing is for a business or commercial purpose, the regulations provide an exception for qualifying credit above $10,000 and up to $500,000 where the APR does not exceed 48%, as well as for qualifying credit above $500,000.
The Consumer Protection Act, 2023 should not be presented as current Ontario consumer-credit law because the official Ontario legislation page states that it is not yet in force. The current consumer-protection framework remains the Consumer Protection Act, 2002 and its applicable regulations.
Understanding Ontario Loan Agreements
What Is an Ontario Loan Agreement?
An Ontario loan agreement is a legal contract where:
- One person lends money
- Another person agrees to repay it under clear terms
Under Ontario law, this can apply to:
- Personal loans (friends/family)
- Business loans
- Private lending arrangements
Verbal vs Written Agreements
An oral loan agreement can create legal obligations, but proving exactly what the parties agreed to can be much harder when there is no written record.
| Type | Risk Level | Proof |
| Verbal Agreement | Higher evidentiary risk |
Terms may be harder to prove
|
| Written Agreement | Clearer evidence |
Written terms document the parties’ agreement
|
A written agreement can reduce confusion by recording the loan amount, repayment date, interest rate and other agreed terms.
When Should You Use a Loan Agreement?
Use a written loan agreement when money is being lent and the parties want clear repayment terms, especially for:
- Lending to friends or family
- Funding a startup or business
- Employee loans
- Private lending deals
Real-life example:
You lend $5,000 to a friend. There is no written agreement and no clear repayment date. After six months, your friend says, “I thought it was a gift.”
A written agreement would have provided clearer evidence of the amount advanced and the repayment obligation.
Is a Loan Agreement Legally Enforceable in Ontario?
A loan agreement may be enforceable when the parties have formed a valid contract and the terms are sufficiently clear and lawful. Offer, acceptance and consideration are relevant contract concepts, but they are not the entire legal analysis.
A loan arrangement may involve:
- Offer → One party proposes the loan terms
- Acceptance → The other party agrees to those terms
- Consideration → The loan and repayment obligations form part of the contractual exchange
Courts can also consider the wording, certainty, legality, capacity and circumstances surrounding the agreement.
When it may NOT be enforceable:
Potential problems can include:
- No clear evidence that the parties agreed to the terms
- Vague repayment terms
- An interest provision that conflicts with applicable law
- Missing important contractual details
While loan agreements focus on financial terms, in some cases confidentiality clauses may apply, which are explained in the Ontario NDA template guide.
Key Terms Every Ontario Loan Agreement Must Include
Loan Amount and Currency
Always write the amount clearly in Canadian Dollars (CAD).
For example:
Loan Amount: $5,000 CAD
Interest Rate (and Legal Limits)
Under section 347 of the Criminal Code and the Criminal Interest Rate Regulations, an APR exceeding 35% is generally a criminal rate of interest, subject to statutory exceptions and regulations. Certain qualifying business or commercial borrowings are treated differently under the regulations.
When setting interest:
- State the rate clearly
- Explain how it is calculated
- Make sure the rate and related charges comply with applicable federal and Ontario law
Repayment Schedule
Choose one:
- Lump sum (one payment)
- Installments (monthly/weekly)
Always include exact dates.
Default and Late Fees
Explain:
- What happens if payment is late
- Any penalties or extra fees
- When the borrower is considered in default
Any interest, fee or penalty should be reviewed for compliance with applicable law.
Security (Optional)
- Secured loan → backed by an asset or other collateral
- Unsecured loan → no collateral is provided to secure the debt
Governing Law Clause
Always include:
“This agreement is governed by the laws of Ontario.”
Secured vs Unsecured Loans
| Type | Meaning | Risk |
| Secured Loan | Backed by collateral |
Gives the lender rights against the collateral, subject to applicable law
|
| Unsecured Loan | No collateral |
Recovery depends primarily on the borrower’s repayment obligation and applicable enforcement process
|
Example:
- Secured → Borrower gives a car as collateral
- Unsecured → No collateral is provided
Key insight:
If the borrower defaults, properly created security may give the lender enforcement rights against the collateral, subject to the security agreement, registration requirements and applicable law.
How to Fill Out the Ontario Loan Agreement
Follow this simple process:
Step 1: Add Names and Addresses
Use full legal names and correct addresses.
Step 2: Define Loan Amount and Interest
Be exact. Avoid vague numbers.
Step 3: Choose Repayment Structure
Decide:
- One-time payment OR
- Installments
Step 4: Add Clear Dates
Include:
- Loan start date
- Repayment dates
Step 5: Sign the Agreement
Both parties should sign the agreement so there is clear evidence that they accepted its terms.
Important tip:
Each person should keep a signed copy.
This document can also relate to a partnership agreement or a contract drafting guide when structuring more complex financial arrangements.
Common Mistakes to Avoid
A few drafting gaps can create avoidable problems when a borrower misses a payment or disputes the debt:
- No repayment dates
- Illegal or unclear interest rates
- No clear evidence that the parties agreed to the terms
- Using vague language
- Ignoring default clauses
Practical tip:
If something feels “understood,” write it down anyway.
Legal Risks of Not Using a Loan Agreement
A written loan agreement does not guarantee recovery, but it can make a debt dispute easier to analyze by documenting the amount advanced, repayment date, interest, default terms and the parties’ obligations.
Scenario:
A business owner lends $10,000 to a partner and records the loan in a signed agreement. If the partner later disputes the repayment obligation, the written terms give both sides clearer evidence of what was agreed.
Interest Rates and Canadian Law
Under the Criminal Code of Canada, s. 347, and the Criminal Interest Rate Regulations (SOR/2024-114):
- Consumer/Personal Loans: An annual percentage rate exceeding 35% is generally a criminal rate of interest, subject to statutory exceptions.
- Commercial Loans: For certain business or commercial borrowings where the borrower is not a natural person, the regulations provide an exception where the credit is more than $10,000 but no more than $500,000 and the APR does not exceed 48%. Credit exceeding $500,000 can also fall within the regulatory exception.
Why this matters:
The definition of “interest” under s. 347 is broad and can capture various charges connected with the credit, subject to the statutory definitions and exclusions. A loan involving a criminal rate can create serious criminal and civil consequences, so the rate and associated charges should be reviewed carefully before the agreement is signed.
Keep interest:
- Fair
- Transparent
- Clearly written
Loan Agreement vs Promissory Note
| Feature | Loan Agreement | Promissory Note |
|---|---|---|
| Detail Level | Can contain detailed terms | Usually focuses on the promise to pay |
| Legal Protection | Depends on the terms and applicable law | Depends on the terms and applicable law |
| Best Use | Loans with multiple conditions | Simpler repayment arrangements |
Use a loan agreement when:
- Large amount involved
- Multiple conditions exist
Use a promissory note for simple repayment promises.
You can also explore our Ontario Promissory Note template for simpler lending situations.
FAQs About Ontario Loan Agreements
Do I need a lawyer to create a loan agreement?
No, you do not always need a lawyer to prepare a loan agreement. For simple loans, a clear written agreement may be sufficient, but legal advice can be useful for large, secured or complex transactions.
Can I lend money without interest in Ontario?
Yes. Parties can agree to an interest-free loan, provided the arrangement complies with applicable law and the agreement clearly states that no interest is payable.
Is a handwritten loan agreement valid?
A handwritten loan agreement can be enforceable if the parties formed a valid contract and the terms are sufficiently clear, subject to any applicable statutory requirements.
What happens if the borrower doesn’t pay?
If the borrower does not repay, the lender may have legal options to enforce the debt. Depending on the amount and circumstances, a claim may be brought in Small Claims Court or another appropriate court. Ontario’s Small Claims Court currently has a monetary jurisdiction of up to $50,000.
Can I change the agreement later?
Yes, the parties can generally agree to change the terms of a loan agreement. Put any amendment in writing and have the parties sign it so there is clear evidence of the revised terms.